THE CLIMATE
INSURANCE COLLAPSE
When risk becomes reality, who pays the price?
- SKYROCKETING PREMIUMS.
- CANCELLED POLICIES.
- UNINSURABLE HOMES.
- SKYROCKETING PREMIUMS.
- CANCELLED POLICIES.
- UNINSURABLE HOMES.
- SKYROCKETING PREMIUMS.
- CANCELLED POLICIES.
- UNINSURABLE HOMES.
- SKYROCKETING PREMIUMS.
- CANCELLED POLICIES.
- UNINSURABLE HOMES.
Our financial system wasn't built for this.
The Next Financial Crisis Isn’t on Wall Street. It’s in Your Mailbox.
For decades, home insurance was designed to protect us from the possibility of disaster. But in a changing climate, damage isn’t possible. It’s inevitable. And when risk becomes certain, the entire system breaks:
Premiums
Soar
Policies
Vanish
Mortgages Disappear
Markets Collapse
This is not just about protecting the people and places we love. It’s also about protecting their future and the opportunities we have to own a home.
How Extreme Weather Is Breaking Insurance—and What Comes Next
A changing climate → Higher risk
Wildfires, floods, hurricanes, and storms are becoming more frequent and more destructive.
Higher risk → Higher costs
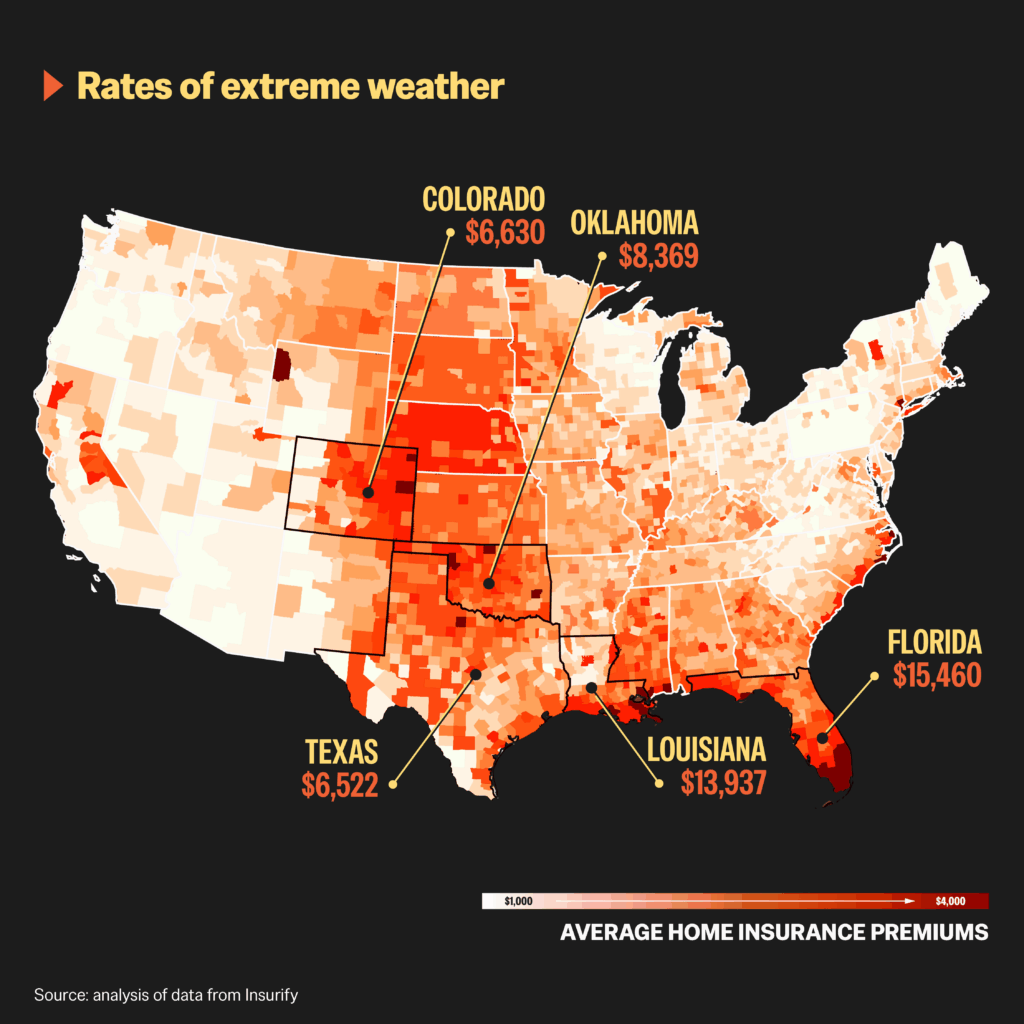
Premiums rose in 95% of zip codes across this county in the past year.
Rising costs → Less coverage
Insurers are having to leave vulnerable markets, leaving homeowners unprotected.
No insurance → No mortgages
If you can’t insure it, you can’t finance it. As if it wasn’t already hard enough to afford a house.
No mortgages → Economic collapse
When housing markets crash, the economy follows.
This chain reaction is already in motion; so who’s going to pay for it?
If we don’t have protection with insurance, we’re going to lose so much. I’m worried about losing the house.
-Marcella C, Los Angeles
The risk has gone up. Year over year, the hurricanes are getting worse. I have flooding in a house that never had anything happen to it before.
-Vatche T, Florida